With $58.9B in claims paid in 2025 & $2.2B in estimated fraud.
Has Your Approach Changed?
Reduce Fraud Exposure with Drone, ROV & Digital Twin Data Insights
Increasing Clarity. Accelerated Decisions. Building Confidence
CASA ReOC 9076
|
ISO 9001
ISO 45001
ISO 14001
Aligned
|
$20M Public Liability
|
CASA ReOC 9076 | ISO 9001 ISO 45001 ISO 14001 Aligned | $20M Public Liability |
Paying the Compounding Cost of Slow & Subjective Assessments
Volume:
$4.8 billion in insured losses from 294,000 claims in 2025 alone, driven by extreme weather events that are increasing in both frequency and severity.
Ex-Tropical Cyclone Alfred generated 132,000 claims in a single event. Can your field assessors physically reach every property fast enough?
$4.8B | 294,000 claims | 5 declared catastrophes in 2025 alone (ICA, 2026)
Process:
Your current process has structural weaknesses. Ground-based adjusters face safety risks on damaged structures. Flood-affected areas are inaccessible for days. Manual inspections are subjective, inconsistent, and slow.
Every day of delay compounds policyholder distress, increases operational costs, and exposes you to complaints and regulatory scrutiny.
2-4hrs | Per traditional property assessment, including travel
Fraud:
An estimated $2.2 billion is lost to fraudulent claims annually. Without objective, timestamped, high-resolution evidence captured at the point of loss, your fraud detection relies on subjective information. Only $560 million was detected as opportunistic fraud in 2023 alone; undetected fraud is estimated to be almost 75% higher.
$2.2B | Annual fraudulent claims (IFBA)
If your adjusters visit one property at a time:
After a major event, the queue stretches for weeks. Every day compounds policyholder distress, increases operational costs, and exposes you to complaints. At 2-4 hours per traditional assessment, including travel, a backlog of 294,000 claims is impossible.
If you rely on desk-based aerial imagery (Nearmap, EagleView, satellite):
Your imagery is weeks or months old by the time of the claim. Top-down only. 5 - 30 cm resolution or worse cannot accurately identify membrane failures, measure crack width, detect solar panel damage, or moisture ingress.
When a cyclone hits, you wait for the area’s next scheduled capture. You cannot produce evidence that holds weight in disputed claims.
If you have tried an in-house drone program:
You are carrying fixed costs for variable demand that changes rapidly. Two pilots cannot become twenty during a CAT event. Your technology freezes at the time you purchased it. When you need advanced sensors - thermal, underwater, confined space, or ground-level 360 capture and the capabilities to both analyse and report, you are quickly back to outsourcing.
You’re managing aviation regulatory compliance, pilot currency, digital twin accuracy, and data processing and analysis. If you believe you should work as an insurer, not as an aerotech company, call us today.
Results at Scale
Up to 30%
Reduction in loss adjustment expenses
Approx $100,000+
Saved per estimator, per year
Estimate of up to 37%
Faster Claims Settlement times
Up to 60%
Reduction in inspection backlogs during peak disaster times
Built for Insurance Professionals Who Need Better Evidence, Faster
Whether you are managing claims, pricing risk, investigating fraud, or responding to catastrophe events
Claims Directors & Loss Adjusting Managers
Backlogged assessments, rising LAE, policyholder complaints escalating during CAT events. Your team cannot physically reach every property fast enough, and every day of delay compounds cost.
Underwriting & Risk Managers
Pricing premiums on assumptions, not data. No property-level condition intelligence. Reinsurers demanding better data. Drive-by photos and Google Street View are not evidence.
CAT Response & Surge Operations
Fixed team cannot scale. Two pilots cannot become twenty. Procurement takes weeks when disaster strikes. 132,000 claims from a single cyclone overwhelms any internal capacity.
Fraud & Special Investigations
$2.2 billion lost to fraudulent claims annually. 75% goes undetected. No pre-loss baseline. Relying on adjuster judgment and inconsistent documentation that cannot withstand scrutiny.
Property & Strata Portfolio Managers
Managing hundreds of properties with no standardised condition data. Maintenance decisions based on complaints, not evidence. Capital works budgets based on estimates, not measurements.
Subrogation & Recovery Teams
Proving third-party liability requires evidence that the damage was caused by their negligence, not pre-existing conditions. Without objective before-and-after documentation, recovery claims are contested and abandoned.
Claims Acceleration:
A Structured Program
Up to 500%
Productivity Improvement for Remote Adjusters
Up to 400%
Faster Claims Estimation
After a catastrophic event, you can capture the entire affected area within 48 hours.
Your desk-based adjusters remotely navigate to any property in the dataset, measure damage, and complete assessments.
One mobilisation covers hundreds of properties. Pre-loss baselines already exist for your high-value portfolios. Evidence is measurement-grade, timestamped, and holds up in any dispute.
Traditional Assessment vs. Structured Intelligence Program
A managed inspection program does not just reduce cost. It creates intelligence infrastructure that compounds in value across routine operations and catastrophe response alike.
Traditional (Reactive)
One property. One visit. One report. No cumulative value. Same cost whether routine or urgent.
Structured Program (Capture)
Scheduled captures for BAU. Surge capacity for CAT. Standardised data builds portfolio intelligence over time.
Platform Intelligence (Digital Twin)
AI-powered. Portfolio-wide. Predictive. Routine monitoring prevents claims. Event response is instant because the baseline already exists.
Assessment Cost
Traditional
$500 - $1,500+ per property. Adjuster travel, time on-site, admin overhead. Same cost whether it is a routine renewal inspection or a post-event claim.
Structured
From $250 per property. Batch capture, processing, condition report, platform delivery. Volume pricing at program scale reduces cost further for annual portfolios.
Platform
Decreases over time. Subsequent captures are faster because the baseline already exists. Routine annual captures cost less each cycle. Post-event assessment is near-instant because only change needs evaluation.
Assessment Speed
Traditional
Days to weeks. Schedule adjuster, travel, wait for report. One property at a time. Routine renewal inspections compete for the same limited field capacity as claims.
Structured
Routine: Scheduled captures aligned to renewal cycles, completed in predictable timeframes. Event: Same-day to 48hrs batch capture of entire affected zones. Reports within days either way.
Platform
Routine: Automated change detection flags deterioration between scheduled captures. Event: Pre/post overlay available the moment post-event data is uploaded. AI flags changes automatically. No waiting for a human to compare.
Scalability & Program Flexibility
Traditional
Fixed capacity regardless of demand. Routine inspections backlog when claims spike. CAT events create 1-4 week queues. Overtime rates. Adjuster burnout. No flex between BAU and surge.
Structured
BAU: 5 properties this month, 50 next quarter — scales to your renewal schedule without fixed headcount. CAT: Same infrastructure pivots to area-wide response within 24-48hrs. No idle capacity cost between events.
Platform
Force multiplier in both modes. Routine: One scheduled capture serves underwriting, claims, and portfolio management teams simultaneously. Event: One capture serves unlimited desk adjusters. Portfolio-wide triage from a single dataset regardless of whether it is BAU or disaster.
Data Consistency
Traditional
Varies by adjuster. Handheld photos, inconsistent angles, no measurements. Quality depends on individual. Routine inspections and claims assessments produce incomparable data.
Structured
Standardised. Calibrated sensors, consistent methodology, georeferenced, measurement-grade. Every property captured the same way whether it is a routine annual baseline or a post-event assessment. Data is directly comparable year-over-year.
Platform
Machine-readable. AI defect detection (cracks, spalls, roof condition). Automated condition scoring. Quantified measurements, not subjective opinion. Consistent grading across your entire portfolio enables benchmarking and trend analysis.
Fraud & Dispute Prevention
Traditional
Reactive. No pre-loss baseline. Relies on adjuster judgment. 75% of fraud goes undetected (IFBA). Routine inspections produce no evidence usable in future disputes.
Structured
Proactive. Routine annual captures create the pre-loss baseline automatically. When a claim is lodged, post-event comparison shows exactly what changed and when. The baseline you built during BAU becomes your strongest evidence during a dispute.
Platform
Evidence-grade. Measurement overlay quantifies damage. Metadata integrity (GPS, time, calibration). Eliminates ambiguity that fraud relies on. AI flags discrepancies between pre-loss and post-loss automatically. Routine monitoring makes fraud nearly impossible to sustain.
WHS Exposure
Traditional
High — in both routine and emergency scenarios. Routine roof inspections still require height access, edge protection, and harness systems. Post-event: personnel on damaged roofs, in flood zones, near structural collapse. Premium workers comp costs regardless of whether it is BAU or CAT.
Structured
Eliminated. Remote capture for routine renewals and post-event assessment alike. No personnel on roofs, damaged structures, or in confined spaces. Zero height-at-work exposure whether you are capturing an annual baseline or documenting cyclone damage.
Platform
Documented. Platform records all access decisions and methodology. Audit trail for WHS compliance across routine and emergency operations. Evidence for subrogation if third-party negligence caused the damage. Your duty of care is demonstrably met.
Portfolio Visibility
Traditional
None. Individual claim files in separate systems. No aggregate view. No predictive capability. Routine inspections produce isolated reports that never connect to portfolio strategy.
Structured
Asset-level. Each property has a condition record updated with every scheduled capture. Searchable, measurable, comparable. Your routine program builds the portfolio intelligence that informs renewal decisions and capital planning.
Platform
Portfolio-wide intelligence. Deterioration tracking across all assets over time. Risk concentration mapping. Renewal pricing informed by actual condition data, not postcode averages. Predictive maintenance triggers alert you before a claim occurs.
Underwriting Support
Traditional
Limited. Drive-by photos or Google Street View. No interior, no thermal, no measurement. Underwriters price risk on assumptions because objective property data does not exist at the point of policy issuance.
Structured
Comprehensive. Aerial, thermal, interior 360, facade. Full property envelope captured before policy issuance as part of your routine underwriting workflow. Condition data available at the point of risk decision.
Platform
Risk-priced. AI condition scoring informs premium calculation. Thermal identifies hidden risks (moisture, electrical) before they become claims. Objective data replaces assumptions. Annual recapture tracks whether the insured is maintaining the property to the standard you priced for.
Recurring Value
Traditional
Zero. Each assessment is a one-off cost. No cumulative benefit. No learning. Last year's inspection report has no connection to this year's. You start from scratch every time.
Structured
Builds over time. Annual captures create a condition history. Each year's data is more valuable than the last because it enables comparison. Your routine program creates the evidence base that protects you during disputes years later.
Platform
Compounding intelligence. Multi-year deterioration models predict which properties will generate claims. Routine monitoring prevents losses before they occur. Claims forecasting from actual asset behaviour, not actuarial tables alone. The longer you run the program, the more valuable it becomes.
Estimate Your Program Savings
Enter your portfolio details to see the annual value of a structured inspection program versus reactive, one-off assessments.
Value Breakdown
Platform Intelligence Value (Not Quantified Above)
These estimates are conservative. They do not include speed-to-settlement value, reduced complaints, or reinsurer premium benefits from improved data quality.
Get my program proposal → Call Direct: 0492 449 655What Should Your Structured Program Look Like
Three Ways to Start. One Path to Continuous Improvement.
Service Tier 1: On-Demand Assessment
For: Individual property claims, underwriting inspections, and dispute evidence
Your adjuster needs evidence for a specific property. A single mobilisation captures the complete condition record across all environments the property requires: roof, facade, surrounds, interior, and substructure. Sub-centimetre resolution. Georeferenced. Timestamped. Delivered within 5 business days.
Pricing indicator: From $250 per property (image capture, batch assessment). Condition reports and 3D models priced on scope.
What You Receive
Sub-centimetre imagery from all angles (not just top-down)
Thermal overlay identifying hidden moisture and leak paths
Georeferenced, timestamped evidence package with chain of custody
Optional interactive 3D model with measurement tools
Delivered within 5 business days of capture
What It Replaces
Weeks of individual site visits across the zone
Queue of 200+ properties waiting for one assessor
Dispute over what was pre-existing damage
Fixed team that cannot surge beyond its headcount
Service Tier 2: Area-Wide Catastrophe Capture
For: Post-disaster or large-scale batch assessment, CAT event response, multi-property claims
With 132,000 claims from a single cyclone, your adjusters cannot physically reach every property. An area-wide capture documents the entire affected zone as a single georeferenced dataset. Multiple desk-based adjusters then navigate the interactive model to their assigned properties and complete assessments remotely from their desks within 48 hours of capture.
What You Receive
The entire affected area captured in one mobilisation
Every property accessible remotely by multiple adjusters simultaneously
Pre/post comparison if an annual baseline exists
Scalable to any event size (network scales, your payroll does not)
Browser-based platform access for your team (no software install)
What It Replaces
Relying on policy inception photos (often years old)
Manual comparison of outdated records
Reactive claims processing after failure
Property-by-property assumptions and conservative pricing
Siloed data in individual claim files
Procurement delay when disaster strikes
Why this matters commercially: You pay for one capture only.
You get remote assessment capability for every property in the zone. Your cost per assessment drops. Your speed increases. Your adjusters handle 3x more claims per day without travelling or leaving their desks.
Service Tier 3: Annual Baseline Program
For: Portfolio risk management, renewal underwriting, fraud prevention, reinsurer data requirements
When a claim arrives, the question is always: "Was this damage pre-existing?" Without a baseline, that question relies on subjective judgment. An annual capture program means the pre-loss evidence already exists. No dispute. No delay. No fraud opportunity.
Your reinsurer wants property-level condition data for renewal pricing. Your underwriting team needs current condition intelligence, not assumptions. An annual program delivers both while simultaneously building the fraud-proof evidence base that eliminates disputes.
Pricing model: Annual program, priced per property per capture cycle. Volume pricing applies. Retainer includes priority CAT response guarantee.
What You Receive
Annual condition capture of high-value/high-risk properties, even prior to policy approvals
Automated change detection between annual captures
Deterioration is identified before it becomes a claim
Portfolio-wide condition scoring for reinsurer reporting
Interactive digital twin platform for underwriting and claims teams
Digital Surface Models and thermal overlays, detecting defects before they’re visible
Priority CAT response mobilisation (retainer benefit)
What It Replaces
Adjuster climbing a damaged roof with a clipboard |
Guesswork about concealed damage |
Subjective photos on a phone with no metadata
Tape measure and estimation
2-4 week traditional assessment timeline
Why this matters commercially: Insurers with pre-loss baselines settle claims faster, detect fraud earlier, price premiums more accurately, meet reinsurer data requirements, and identify deterioration before it becomes a loss.
This is the shift from reactive claims processing to proactive portfolio intelligence.
What Your Adjusters Actually Receive
Every engagement produces measurement-grade deliverables accessible via browser. No specialist software required.
Sub-centimetre aerial capture with AI defect overlay
Roof Condition Orthomosaic
Sub-centimetre resolution aerial capture processed into a georeferenced, measurable map. AI defect detection identifies cracks, membrane failures, ponding, and debris. Every pixel is GPS-located and timestamped.
RGB + Thermal comparison revealing hidden moisture
Concealed Defect Detection
Calibrated radiometric thermal imaging reveals moisture ingress, insulation failures, electrical hotspots, and leak paths invisible to standard photography. Temperature accurate to plus or minus 2 degrees Celsius.
Interactive 3D viewer with annotations and measurements
Interactive 3D Digital Twin
Browser-based 3D model accessible to all authorised parties. Navigate, measure, annotate, and compare pre-loss and post-loss conditions. Multiple adjusters work simultaneously from the same dataset. No software installation required.
Pre-loss baseline vs post-event measurement overlay
Pre-Loss vs Post-Loss Comparison
Measurement-grade overlay showing exactly what changed, when, and by how much. Eliminates disputes about pre-existing conditions. Quantifies damage for accurate scoping. Proves causation for subrogation recovery.
Frequently Asked Questions
For declared catastrophe events, mobilisation begins within 24-48 hours. Area-wide aerial capture documents entire affected zones in a single deployment, creating a georeferenced dataset that multiple desk-based adjusters can access simultaneously. After the 2024 Calgary hailstorm (130,000+ claims), drone-assisted teams completed nearly 1,000 property inspections in five weeks at 6-13 minutes per property. Ground-level, interior, and underwater capture can be integrated into the same mobilisation where required.
A pre-loss digital twin creates a timestamped, measurement-grade record of property condition before any event occurs. When a claim is lodged, adjusters compare the pre-loss baseline against post-event capture to objectively determine what damage is new versus pre-existing. This eliminates the subjective judgment that creates disputes and closes the opportunity for fraudulent claims. The Insurance Fraud Bureau of Australia estimates $2.2 billion in fraudulent claims annually, with 75% going undetected. Objective pre-loss evidence removes the ambiguity that fraud relies on.
Published case studies demonstrate measurable returns: 30% reduction in loss adjustment expense (Bees360/AWS), 37% faster settlement with carriers (Master Restoration/Matterport, 2024), and 3.5 workdays saved per claim through remote assessment alone (ATI Restoration/Matterport, 2021). For batch property assessments starting from $250 per property versus $500-$1,500+ for traditional individual site visits, the cost per assessment drops further at program scale. The primary ROI drivers are reduced site visits, faster cycle times, fewer disputed claims, and lower fraud exposure.
Yes. Data captured using calibrated, enterprise-grade sensors with full metadata chains (GPS coordinates, timestamps, sensor calibration certificates, operator credentials) meets the evidentiary standards required by Australian courts. When captured under an ISO 9001 quality management system with documented chain of custody, this evidence is used in engineering expert reports, insurance litigation, subrogation claims, and dispute resolution proceedings. All deliverables include methodology statements suitable for expert report annexures.
Yes. Interactive 3D models, high-resolution imagery, thermal overlays, and measurement tools are accessed through a standard web browser. No specialist software installation or IT integration is required to begin. Adjusters navigate to any property in the dataset, take measurements, annotate damage, compare pre-loss and post-loss conditions, and complete assessments remotely. Multiple adjusters can work simultaneously across the same dataset, which is how one capture supports hundreds of remote assessments.
The program covers all property types and access environments in a single provider relationship: residential (batch roof assessment), high-rise and strata (facade, balconies, plant rooms), commercial (roof condition, renewal inspections), industrial (complex structures, hazardous environments), agricultural and rural (large-area mapping), marine and waterfront (hull, marina, submerged infrastructure via ROV), and land or broadacre (flood extent, erosion, boundary disputes). Aerial, ground-level 360, confined space, thermal, and underwater capture are combined as needed per property.
Calibrated radiometric thermal sensors detect conditions invisible to standard photography: moisture ingress beneath roof membranes, electrical hotspots indicating fire risk, insulation failures, HVAC leaks, and concealed water damage. Temperature measurements are accurate to plus or minus 2 degrees Celsius. For underwriting, thermal data identifies risks that would otherwise go undetected until they become claims. For claims, thermal evidence establishes causation chains for subrogation by demonstrating that specific defects existed prior to loss events.
Insurance demand is inherently variable. Three properties this week, three hundred next week after a cyclone. A structured program provides surge capacity without fixed headcount. The operator network scales up for catastrophe events and scales down between them, so you are not carrying idle capacity cost. During quiet periods, the program focuses on annual baseline captures, renewal inspections, and portfolio condition monitoring. During events, the same infrastructure pivots to rapid area-wide response with priority mobilisation for program clients.
Individual property assessments start from $250 per property for image capture and batch assessment, with condition reports and 3D models priced on scope. Area-wide catastrophe capture is priced per deployment based on the geographic area and number of properties within the zone. Annual baseline programs are priced per property per capture cycle with volume pricing applied at scale. Program clients receive priority CAT response guarantees as part of their retainer. The cost per assessment drops significantly at program scale compared to traditional individual site visits at $500-$1,500+ each. A scoping discussion defines exact deliverables and pricing structure for your portfolio.
All deliverables are produced in industry-standard formats compatible with existing claims workflows. High-resolution imagery, measurements, and condition reports can be attached directly to claim files within Xactimate, Symbility, ClaimCenter, and other platforms your team already uses. Interactive 3D models are accessed via browser link, requiring no software installation or IT integration. Georeferenced orthomosaics export as GeoTIFF for GIS systems. Measurement data exports in formats that align with Xactimate sketch and measurement tools, allowing estimators to pull verified dimensions directly into their scope of works rather than relying on manual field measurements. We work with your operations team during onboarding to align output formats with your specific system requirements.
We operate Australia-wide from our Gold Coast headquarters, with engagements scoped nationally and internationally. For catastrophe events, our scalable operator network deploys to any affected region within 24-48 hours regardless of location.
Integrated Services
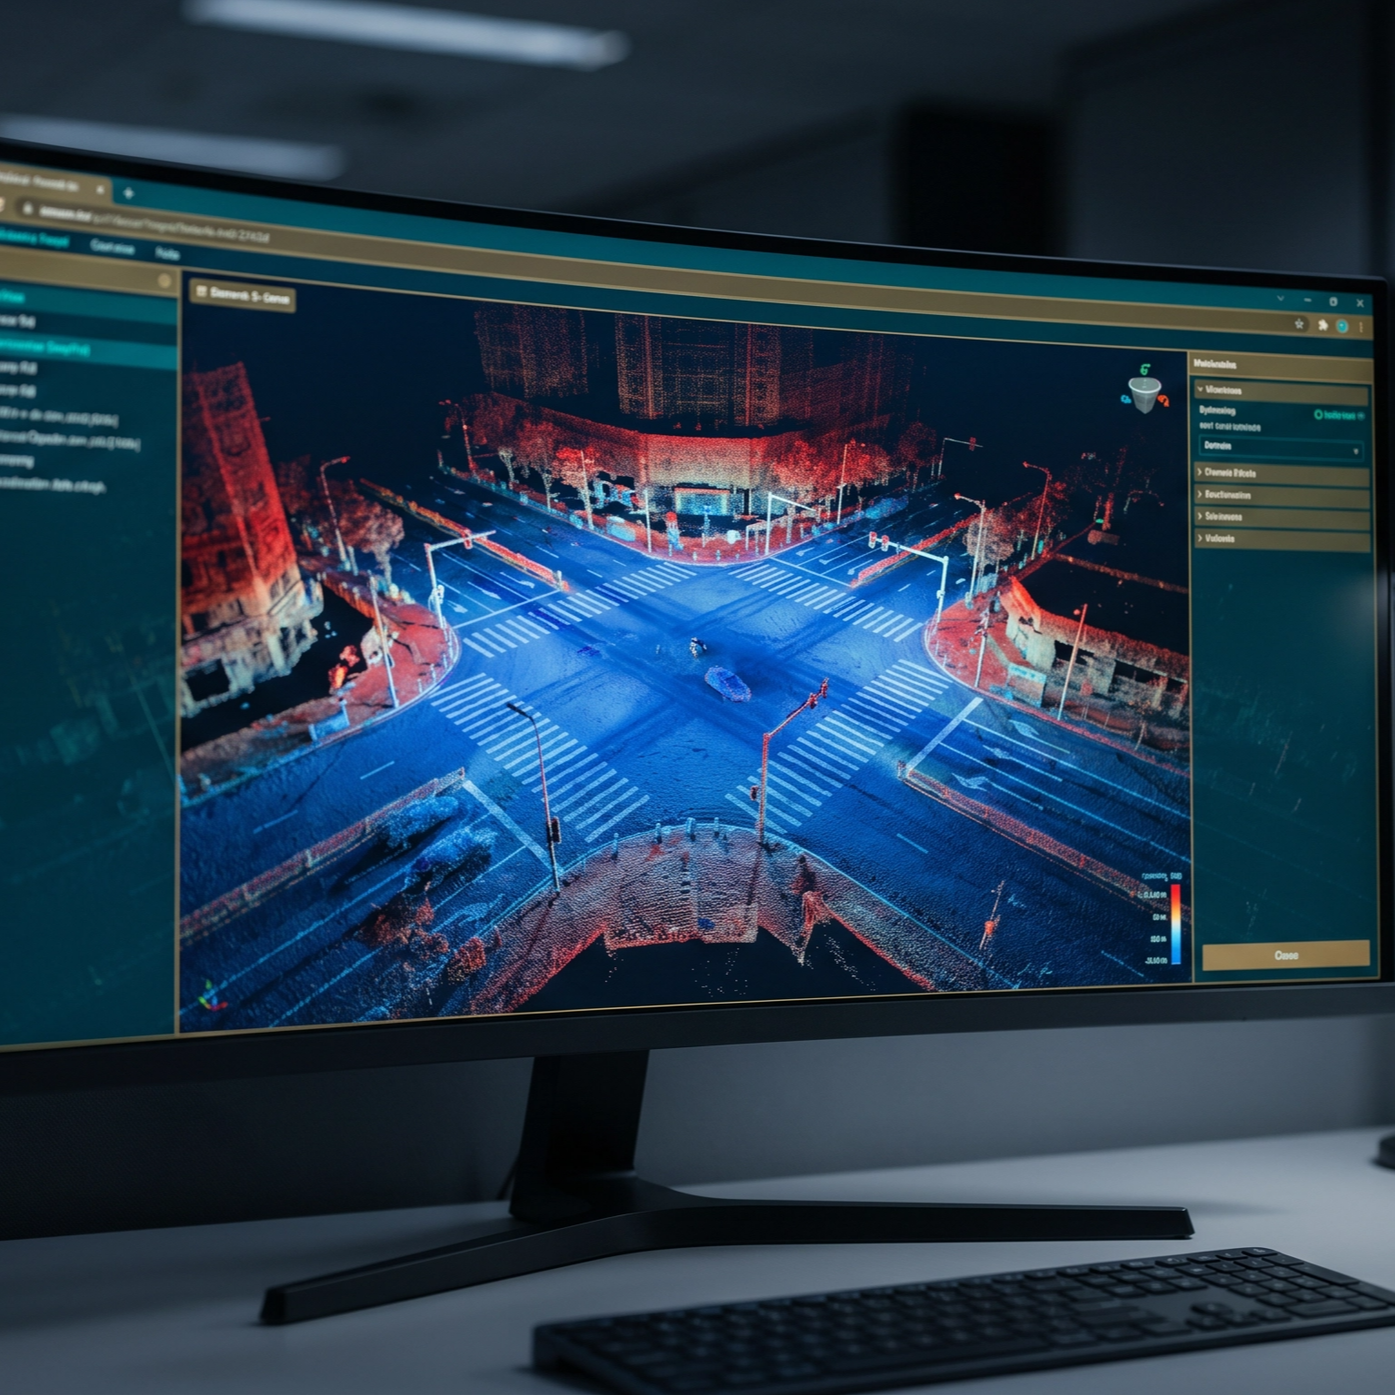
Digital Twin and 3D Modelling
Create exact, interactive digital replicas of assets & incident sites for immersive insights, presentations and remote loss adjustment
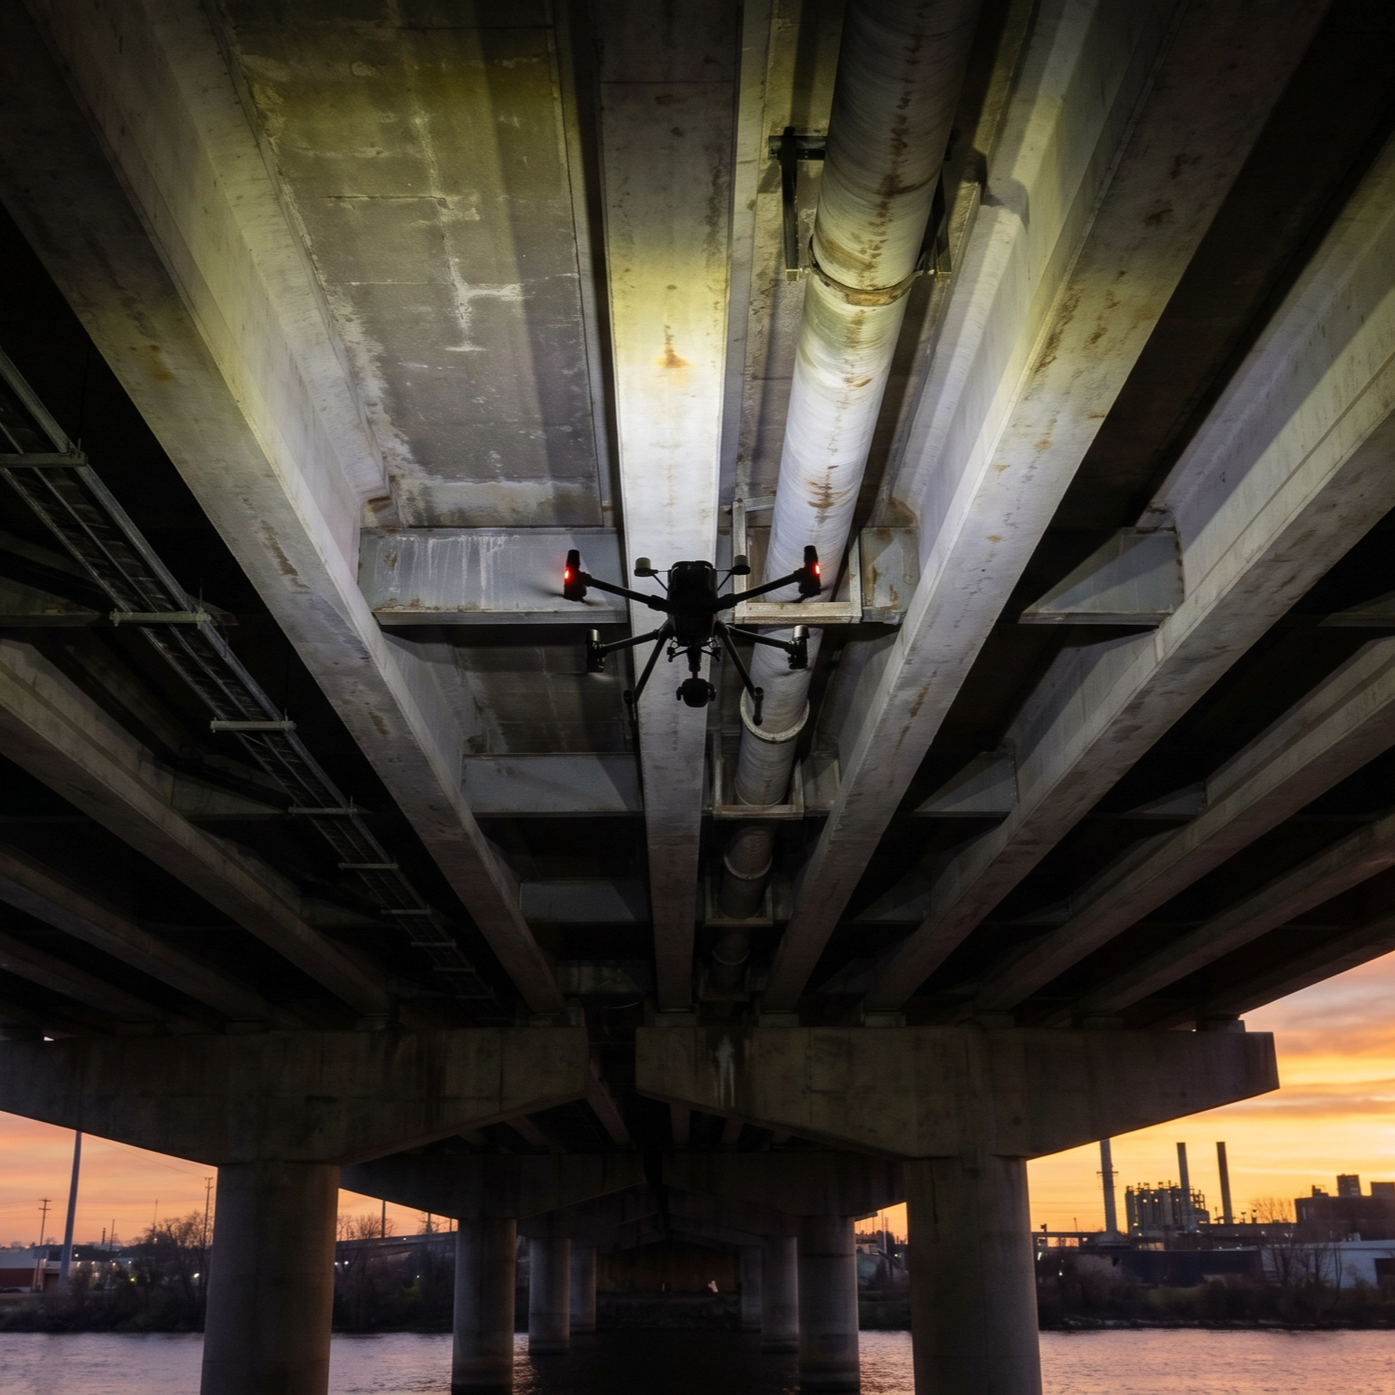
Aerial Inspection and Condition Capture
Rapid, 360-degree high-resolution documentation of condition, damage or claim following natural disasters or asset failures.
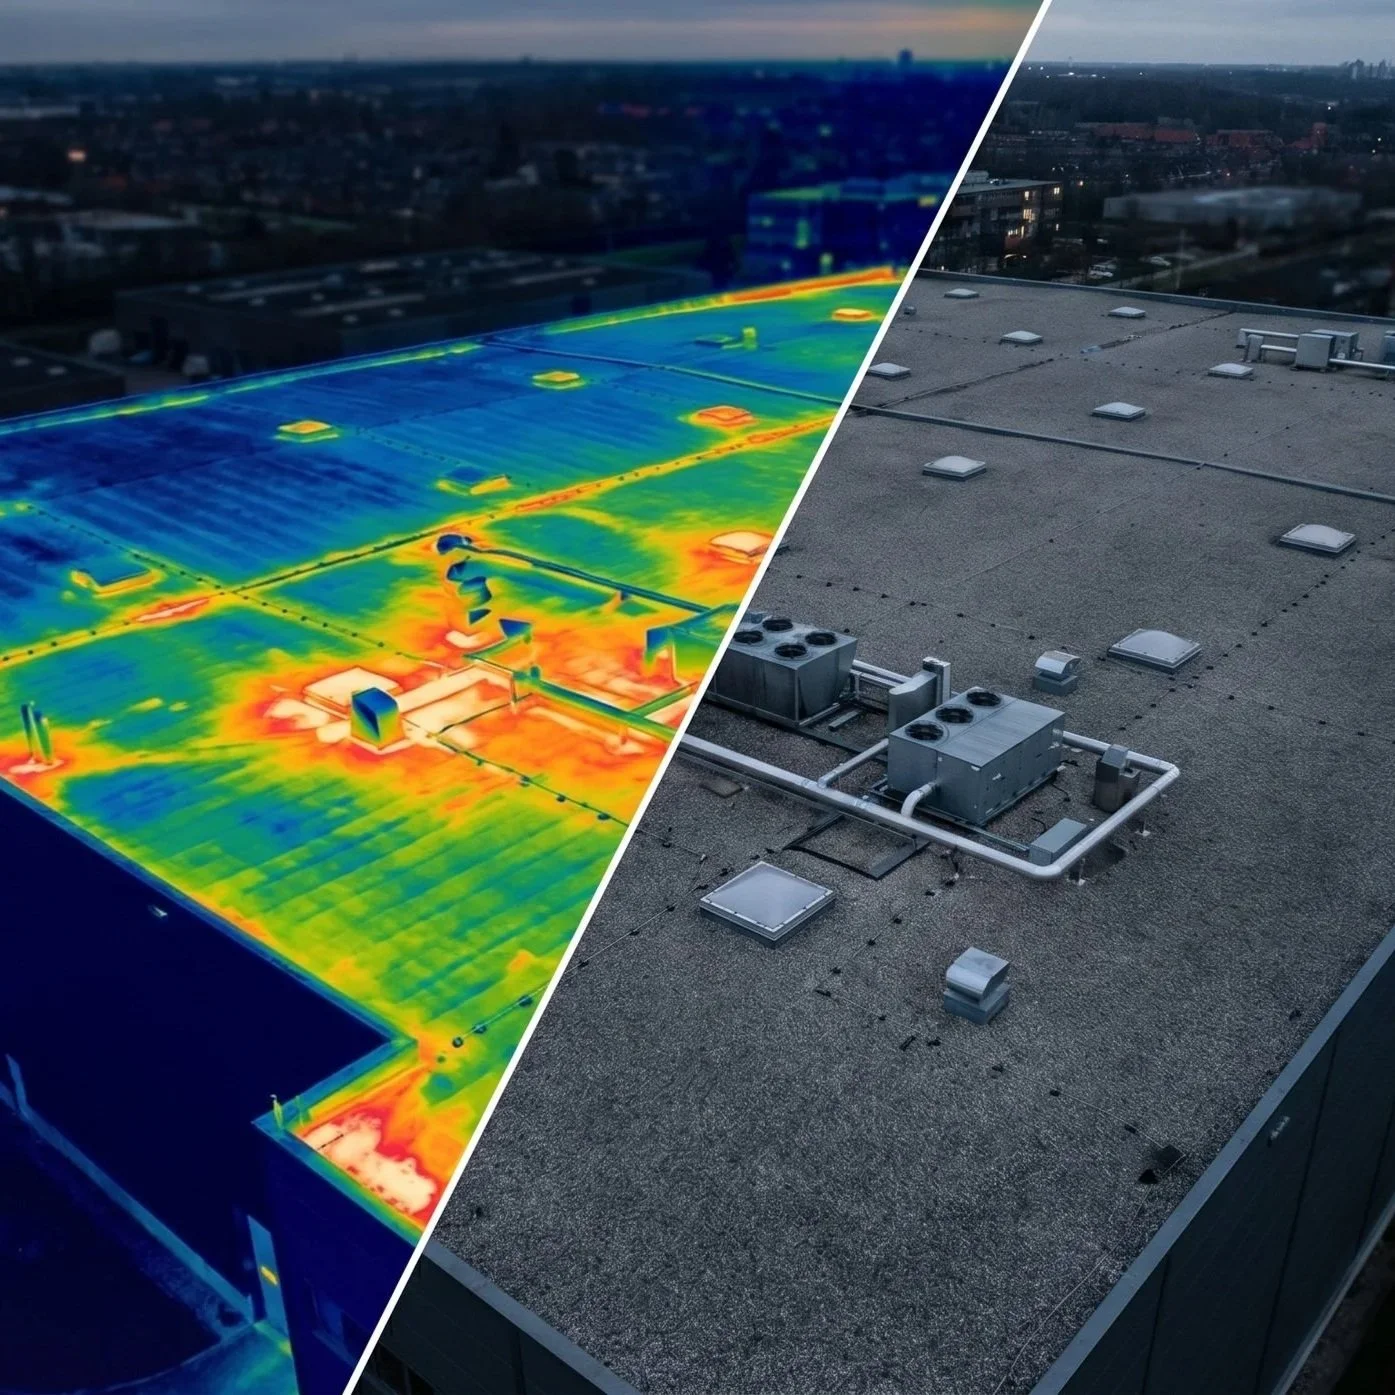
Thermal and Condition Assessment
Detect hidden moisture intrusion, electrical faults, and structural anomalies critical to determining the root cause of a loss.
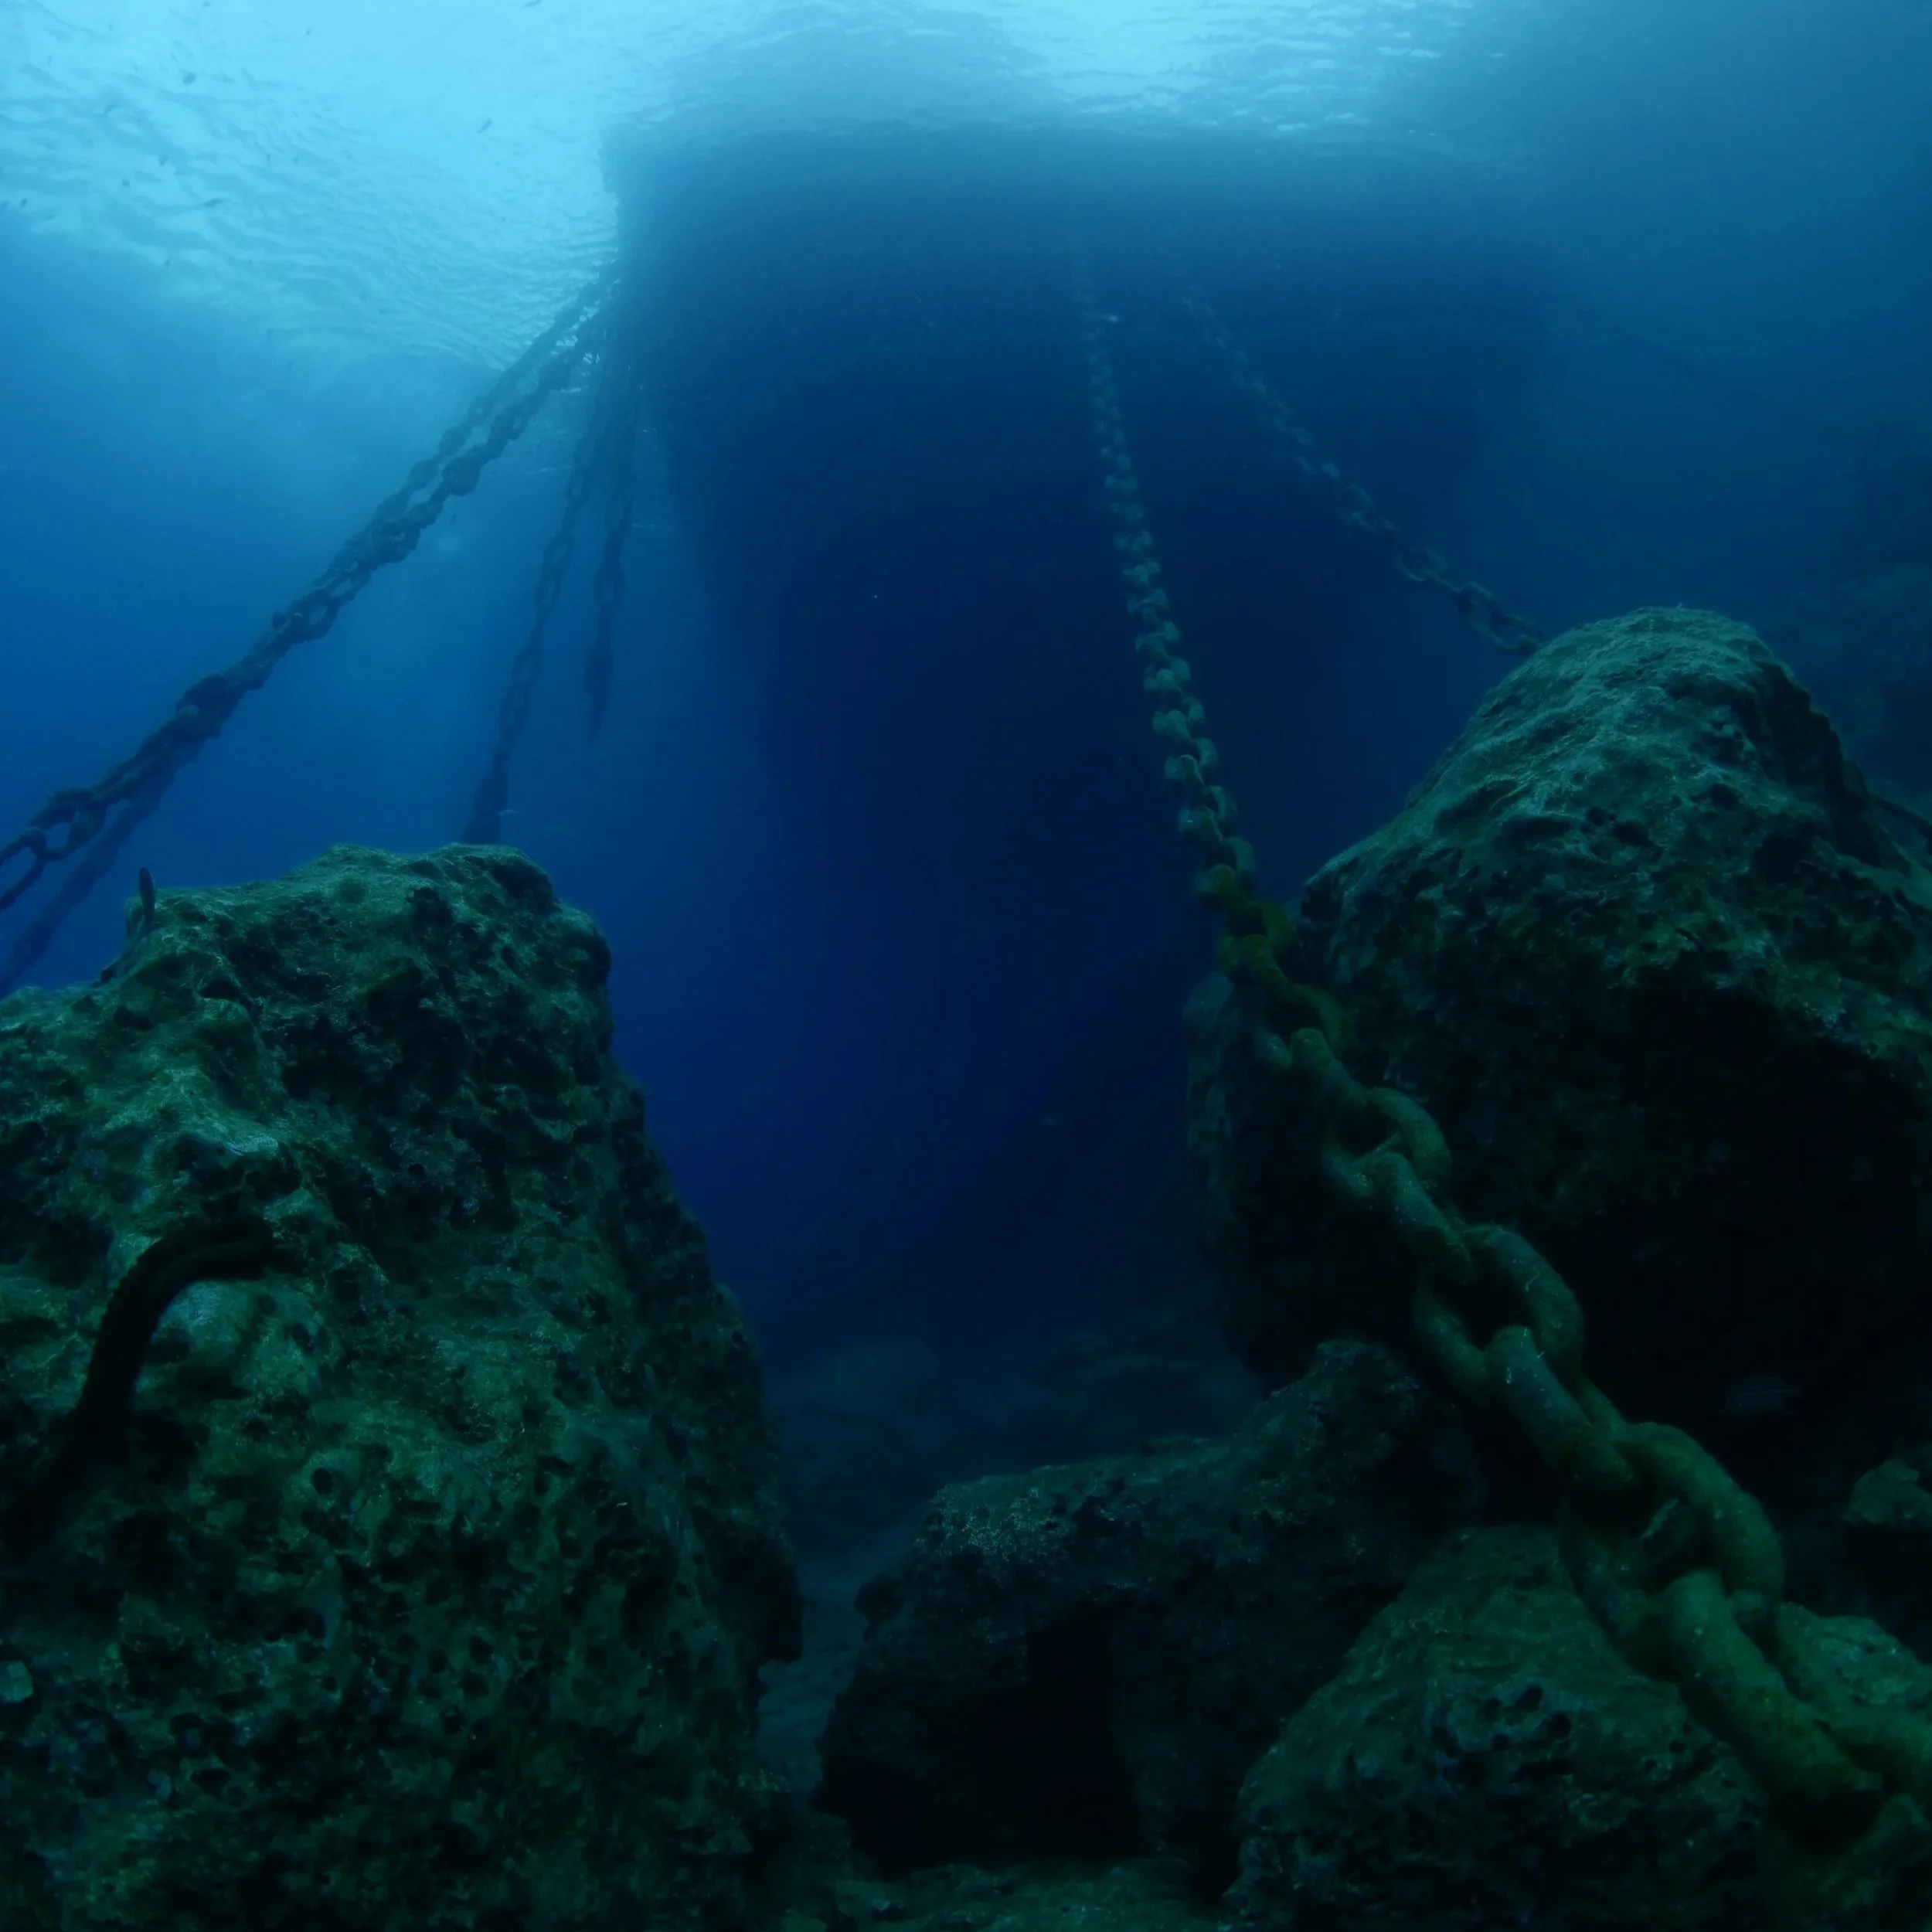
Underwater Asset Inspection & Condition Intelligence
Secure vital information from both above and below the surface, including submerged infrastructure, marine vessels, ports, marinas, and flooded environments, safely and efficiently.